


All
Thought leadership series
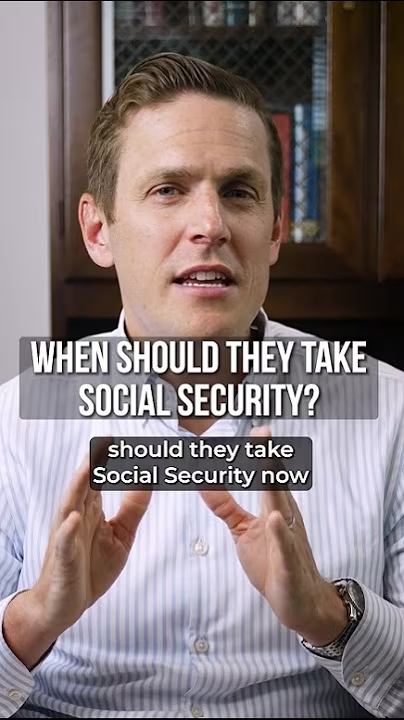
When should my parents start taking social security if they are retiring at 62?
The answer might be different for each spouse. And getting the timing right could mean hundreds of thousands of dollars in additional retirement income. One strategy worth considering? Have the lower-earning spouse claim earlier while the higher-earning spouse waits until age 70. Here's why that can work: 💰 More income early in retirement. The lower earner's benefit can help cover living expenses, including health insurance before Medicare kicks in at 65, and reduce the need to pull money from investments. 📈 A bigger benefit later. By delaying until 70, the higher earner can significantly increase their monthly Social Security check. ❤️ Protection for the surviving spouse. When one spouse passes away, the survivor generally keeps the larger of the two benefits, not both. Maximizing the higher earner's benefit can provide valuable financial protection for the spouse who lives longer. But like most strategies we share, each situation is different and no one strategy is right for everyone. Your health, life expectancy, other income sources, and ability to cover expenses while delaying benefits all matter. And claiming early can permanently reduce the lower earner's benefit. So it’s super important to evaluate this against your specific circumstances to make sure this makes sense for you both. Just remember, the goal is to figure out how to get the most out of Social Security over BOTH of your lifetimes. If you're approaching retirement and haven't run the numbers for both spouses, let's talk. Link in bio.




Osaic Wealth Form CRS
Securities and investment advisory services are offered through Osaic Wealth, Inc., member FINRA/SIPC and a registered investment advisor. Additional investment advisory services offered through Strategic Financial Advisors Corporation, a registered investment advisor. Strategic Financial Advisors Corporation and Strategic Financial Services Corporation are not affiliated with Osaic Wealth, Inc.
This communication is strictly intended for individuals residing in states where the contracted representative is licensed. No offers may be made or accepted from any resident outside the specific state(s) the representative is registered. Current registered states: AZ, CA, CO, CT, DE, FL, GA, KY, MD, NJ, NM, NY, NC, PA, SC, TN, TX, VA. Please contact us to determine the states in which each representative is registered.
Broadridge Investor Communication Solutions, Inc. does not provide investment, tax, or legal advice. The information presented here is not specific to any individual’s personal circumstances.
To the extent that this material concerns tax matters, it is not intended or written to be used, and cannot be used, by a taxpayer for the purpose of avoiding penalties that may be imposed by law. Each taxpayer should seek independent advice from a tax professional based on his or her individual circumstances. Osaic Wealth, Inc. does not provide tax or legal advice.
These materials are provided for general information and educational purposes based upon publicly available information from sources believed to be reliable—we cannot assure the accuracy or completeness of these materials. The information in these materials may change at any time and without notice.
Certified Financial Planner Board of Standards, Inc. (CFP Board) owns the CFP® certification mark, the CERTIFIED FINANCIAL PLANNER™ certification mark, and the CFP® certification mark (with plaque design) logo in the United States, which it authorizes use of by individuals who successfully complete CFP Board’s initial and ongoing certification requirements.
PLEASE NOTE: The information being provided is strictly as a courtesy. When you link to any of the websites provided here, you are leaving this website. We make no representation as to the completeness or accuracy of information provided at these websites. The company is not liable for any direct or indirect technical or system issues or any consequences arising out of your access to, or use of third-party technologies, websites, information, and programs made available through this website. When you access one of these websites, you are leaving our website and assume total responsibility and risk for your use of the websites you are linking to.