


All
Thought leadership series
What should you do financially when a loved one dies? Start here.
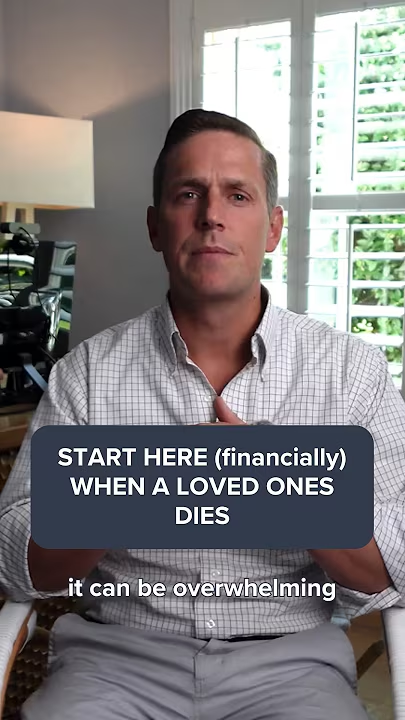
What should you do financially when a loved one dies? First, know what needs to happen immediately and what can wait. Here’s a way to break everything down without feeling overwhelmed. In the first few days, keep it simple. Order extra certified death certificates. Don't throw away the mail or delete their email account. There may be an old 401(k), insurance policy or account you don't know about, and some statements only come once a year. And within the first week or so, call the financial advisor. They can start notifying the right institutions, tell you what information will be needed and coordinate with the estate attorney and accountant. Then slow down. You do NOT need to immediately close every account, move all the money or start distributing the estate. That's where I think a lot of families put unnecessary pressure on themselves. You're grieving. Most of this can wait. And getting the right people involved early will help you stay on track for the things that actually do have real deadlines. There are deadlines around things like estate tax filings and certain estate planning decisions. For example, federal estate tax returns, when required, are generally due nine months after death. A qualified disclaimer also generally has a nine-month deadline. Your financial advisor, estate attorney and accountant can help separate the things that need attention now from the things you don't need to worry about yet. You don't need to know how to settle an estate. You just need to know what needs to happen now, what can wait, and who is helping you through it. If you've recently lost someone and aren't sure where to start financially, we're happy to help. #EstatePlanning #FinancialPlanning #Inheritance




Osaic Wealth Form CRS
Securities and investment advisory services are offered through Osaic Wealth, Inc., member FINRA/SIPC and a registered investment advisor. Additional investment advisory services offered through Strategic Financial Advisors Corporation, a registered investment advisor. Strategic Financial Advisors Corporation and Strategic Financial Services Corporation are not affiliated with Osaic Wealth, Inc.
This communication is strictly intended for individuals residing in states where the contracted representative is licensed. No offers may be made or accepted from any resident outside the specific state(s) the representative is registered. Current registered states: AZ, CA, CO, CT, DE, FL, GA, KY, MD, NJ, NM, NY, NC, PA, SC, TN, TX, VA. Please contact us to determine the states in which each representative is registered.
Broadridge Investor Communication Solutions, Inc. does not provide investment, tax, or legal advice. The information presented here is not specific to any individual’s personal circumstances.
To the extent that this material concerns tax matters, it is not intended or written to be used, and cannot be used, by a taxpayer for the purpose of avoiding penalties that may be imposed by law. Each taxpayer should seek independent advice from a tax professional based on his or her individual circumstances. Osaic Wealth, Inc. does not provide tax or legal advice.
These materials are provided for general information and educational purposes based upon publicly available information from sources believed to be reliable—we cannot assure the accuracy or completeness of these materials. The information in these materials may change at any time and without notice.
Certified Financial Planner Board of Standards, Inc. (CFP Board) owns the CFP® certification mark, the CERTIFIED FINANCIAL PLANNER™ certification mark, and the CFP® certification mark (with plaque design) logo in the United States, which it authorizes use of by individuals who successfully complete CFP Board’s initial and ongoing certification requirements.
PLEASE NOTE: The information being provided is strictly as a courtesy. When you link to any of the websites provided here, you are leaving this website. We make no representation as to the completeness or accuracy of information provided at these websites. The company is not liable for any direct or indirect technical or system issues or any consequences arising out of your access to, or use of third-party technologies, websites, information, and programs made available through this website. When you access one of these websites, you are leaving our website and assume total responsibility and risk for your use of the websites you are linking to.